Specialist mortgage advice for UK dentists
High-street lendersdon't understanddentist income.We do.
NHS contract, private work, limited-company dividends – a specialist broker reads your whole income, not just the one line a computer can read.
Find your situation
Where are you in your career?
Choose the stage of your career, and we'll answer the mortgage questions that matter to you today.
- 01
Foundation dentist
A signed contract, a few months of payslips, and a student loan the affordability calculator does not know what to do with.
Training salaryExtra sessions“Can I buy with only months of payslips?”
9 answers filedOpen the hub - 02
Associate & self-employed
An NHS contract, private work and limited-company dividends – three income streams that a high-street model reads as one, and picks the smallest.
NHS contractPrivate workDividends“Are one year’s accounts enough?”
12 answers filedOpen the hub - 03
Practice owner
Retained profit, a practice loan sitting on your credit file, and accounts written to be tax-efficient rather than mortgage-friendly.
SalaryDividendsRetained profit“Does my retained profit count?”
9 answers filedOpen the hub
Not sure where you fit?Careers rarely land neatly in one box. Talk it through with a specialist adviser before you decide anything.
The bars show how income tends to arrive at each stage. Illustrative proportions.
The problem
The computer reads one line. Your income has three.
A high-street affordability model was built for one salary from one employer. Not every dentist has three income streams – but most have more than one, and the model takes the line it recognises and quietly ignores the rest.
The problem isn't you – it's how lenders see your income.
The same dentist, read twice
Same income · two readingsIllustrative proportions
Neither reading is wrong. They are two lenders applying different criteria to the same person. Finding the one that counts all of your income is the job.
For some lenders one year is enough. Others want two or three, and a few will assess your latest year on its own where the direction of travel is right, meaning upwards. It depends on the lender – this is exactly what we check before an application goes anywhere near your credit file.
Ask a specialist about thisThe full answerAll 12 associate answers
Usually yes, and often sooner than you have been told. Some lenders will work from a signed contract rather than a long payslip history, though the list of lenders who will is short and it changes. Checking which ones are on it today is the part worth doing before you apply anywhere – Wallace Home Finance can help you with this.
Ask a specialist about thisThe full answerAll 9 foundation answers
A handful of lenders will consider your share of retained profit alongside salary and dividends, and for a practice owner that can move the borrowing figure considerably. Most lenders will not. Knowing which ones do is the whole point of asking a specialist.
Ask a specialist about thisThe full answerAll 9 practice owner answers
On a lender that works from drawn dividends, yes – it can understate your income considerably. On a lender that works from net profit, it makes almost no difference. The two are not in conflict; you just need the second kind of lender.
Ask a specialist about thisThe full answerAll 12 associate answers
It is treated as a monthly commitment rather than as a debt held against your name, so it trims what you can borrow rather than blocking you. How much it trims depends on the lender, your repayment plan and how it is represented in your evidence documents. It is rarely the thing that decides the outcome.
Ask a specialist about thisThe full answerAll 9 foundation answers
It will show on your credit file and lenders will ask about it. Where it is serviced by the business rather than by you personally, some lenders will assess it that way once it is properly evidenced. Raise it early with the right paperwork and it is usually manageable.
Ask a specialist about thisThe full answerAll 9 practice owner answers
Nothing filed under that yet – ask a specialist directly.
Proof
Many brokers refused to even help me and I was constantly informed I can’t obtain a mortgage till I work full time … despite having been self employed for 4 years. Luckily I found Joe Wallace…
At the time we were struggling to obtain a mortgage without having to put down a large and ultimately unachievable deposit, as we were both recently qualified self-employed dentists, and so did not have 3 years of accounts behind us.
My partner and I were newly self-employed; Colin helped us navigate the challenges that came with this to ensure we secured a mortgage on reasonable terms and we are now happy home owners.
- 90+lenders
- A panel, not a single bank.
- 10,000+products
- Compared on criteria as well as rate.
- 1adviser, end to end
- First conversation to completion.
- Google Reviews
- Verified by Trustindex. Read them in full on Google.
Want to know what your income actually supports?
All three quotations are clients’ own words, given to Wallace Home Finance and held on file. They are client testimonials rather than Google reviews, and are published with each client’s consent. Each is an excerpt of what the client wrote, shortened but not otherwise changed.
Case files
The same dentist,
read by the right lender.
Three real, anonymised cases. In each one the dentist’s income was what it always was – what changed was which lender was looking, what it was shown, and what its criteria allowed it to accept.
- 01AssociateHandled by Joe Wallace
Two dentists marrying each other. One of them had seen his income fall by more than 20% in a year, and the first lender disregarded his income entirely.
The tax year had already ended, so rather than wait for January he filed his return early. It showed his income back at its previous level, and with an explanation alongside it a different lender counted it. The lending rose by £250,000.
First lender’s offer£400,000Lent£650,000Real figures. One dentist’s outcome, not a guide to yours.
- 02AssociateHandled by Joe Wallace
A first-time buyer six months into self-employment, with no SA302 and no full year of accounts to show a lender.
A building society prepared, under its own criteria, to read an accountant’s projections alongside the statements. The route was found before an application went in anywhere else, so there was no decline on the file.
Usual evidenceDid not exist yetEvidence accepted insteadSix months of pay statements and business bank statements, plus accountant’s projections- Purchase price
- £385,000
- Mortgage
- £308,000
- Loan to value
- 80%
Real figures. One dentist’s outcome, not a guide to yours.
- 03Practice ownerHandled by Joe Wallace
A dentist and her spouse, who worked full time in an unrelated business and took around £20,000 a year in dividends from her company. Their own bank classed the dividends as a second job and would not count them.
A different lender that understood the spouse was taking income as an investor in the company, not working a second job, and counted it. They had been looking for £300,000.
Their bank’s offer£200,000Lent£300,000Real figures. One dentist’s outcome, not a guide to yours.
All three are real cases, anonymised and published with the clients’ consent, with figures supplied by Wallace Home Finance. Criteria and outcomes differ for every applicant, and an outcome for one dentist is not an indication of what another will be offered.
Who reads your file
People, not an
affordability calculator.
Your file is read by a named person who has seen accounts like yours before, and who knows which lenders will read them the same way.
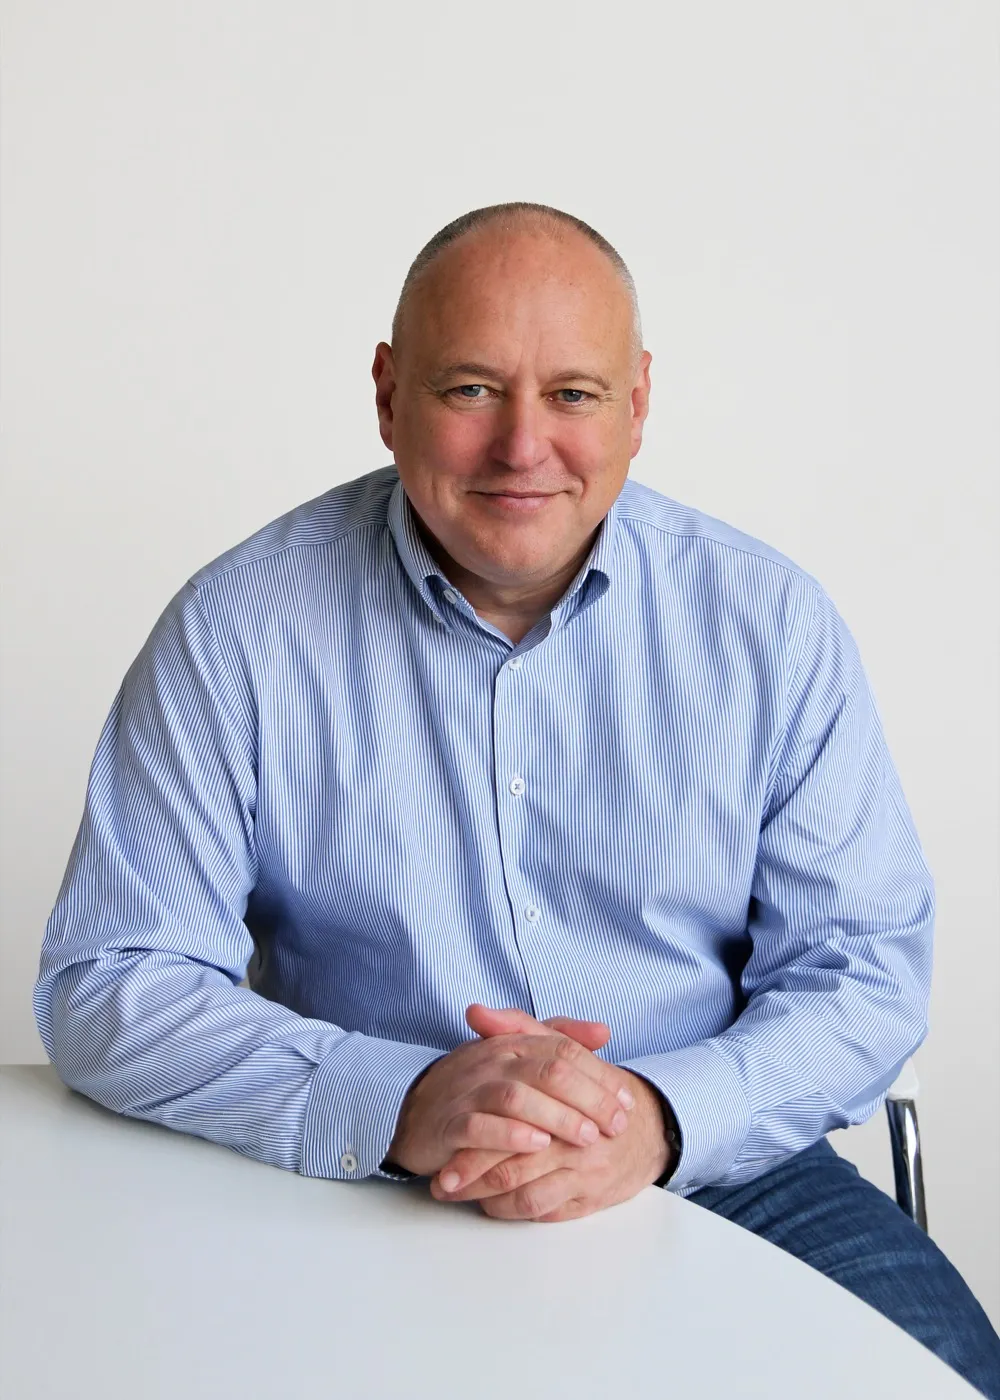
Colin Wallace
Director
I worked with my first dentist in 2019, shortly after I founded Wallace Home Finance, and they were a joy to work with. We had some bumps in the road along their house buying journey, but I came to understand their world and they have become my best clients. I came to understand how dentists are paid, and how difficult it can be for them to obtain mortgages in what should be a very straightforward situation.
I have now supported those first clients through their first and second home purchases and through a major renovation. They have referred many of their colleagues to me, and I hope to work with them for many years to come as their family grows.
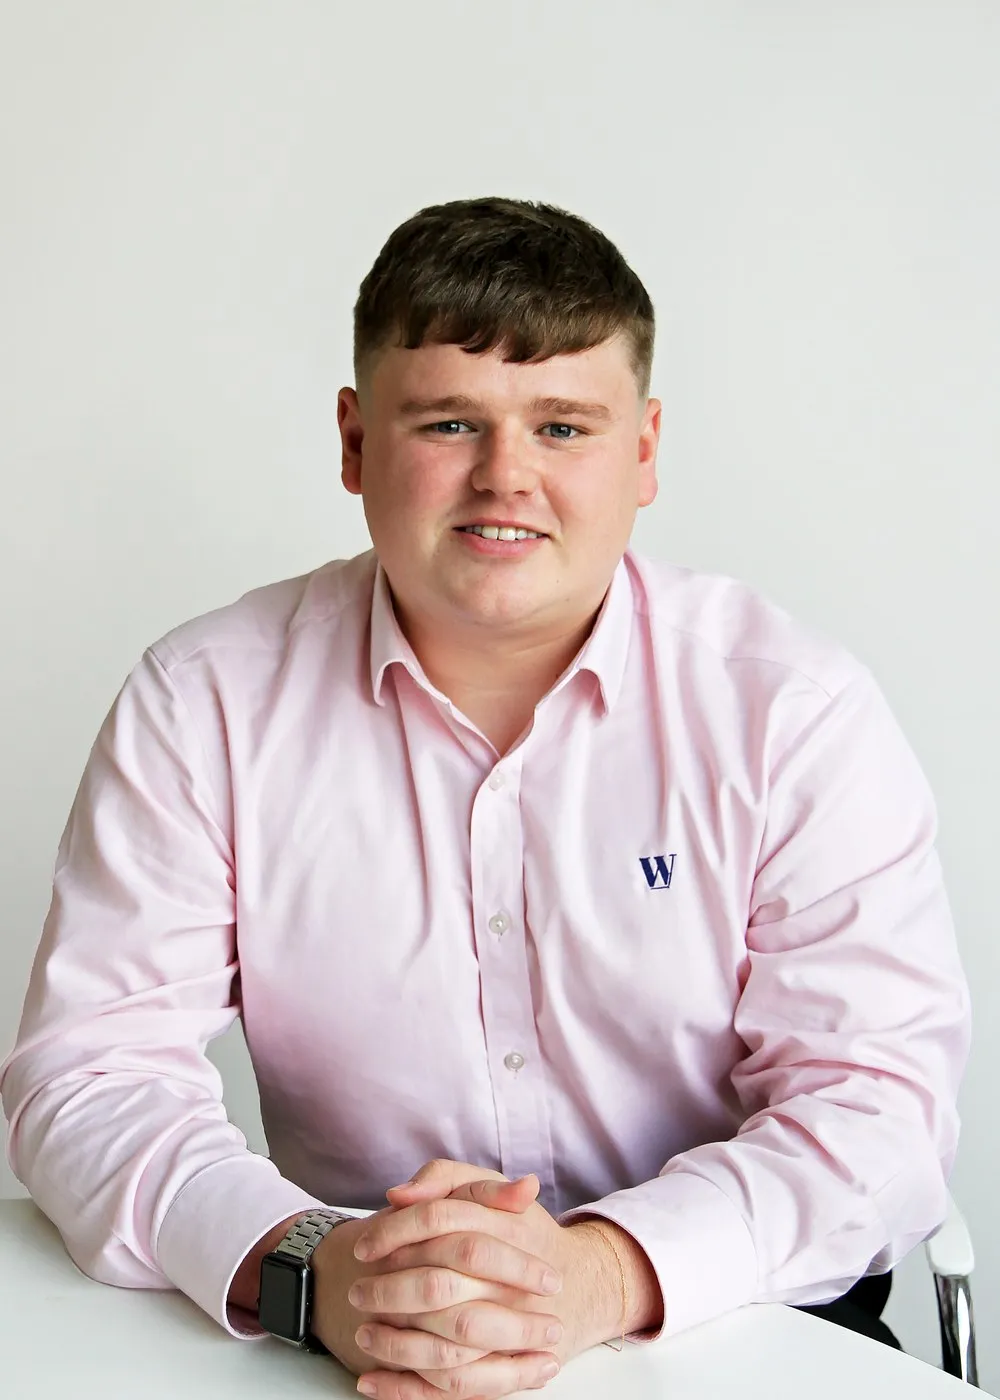
Joe Wallace
Mortgage & Protection Broker
Since entering the industry in 2021, I have worked closely with dentists and developed a strong understanding of the unique challenges they can face when applying for mortgages, from multiple income streams to self-employment and practice ownership.
I enjoy the challenge of finding a solution where the straightforward approach does not work. There is nothing more satisfying than getting a result for a client who has been told elsewhere that their circumstances are too complicated.
- Regulated through
- Mortgage Advice Bureau
- Lender panel
- Around 100 lenders
- Based in
- Leeds · UK-wide
How it goes
- 01
A conversation
What you earn, how it actually arrives, and what you are trying to buy. No credit check at this point.
- 02
The income case
NHS contract, private work and dividends assembled into a picture an underwriter can accept, with the evidence attached.
- 03
The lender search
The panel searched on criteria as well as rate, so the application goes to a lender whose rules already fit you.
- 04
Through to completion
One adviser start to finish, with protection discussed alongside the mortgage rather than after it.
The next step
Ask for the
second opinion.
Tell us how to reach you and a specialist adviser will call back to talk through your income and what it should actually support. Your enquiry goes straight to the team.
Or call directly
0333 054 0747- A conversation first – there is no obligation to proceed.
- Bring your last two years of figures if you have them to hand.
Call me back
Four details. Nothing else needed to start.